Short answer: A 5% rate would make monthly payments a lot cheaper, so more people could afford to buy. But most owners already have a rate below 5%, so far fewer new sellers would show up. In a county that is already short on homes, more buyers chasing about the same number of homes tends to push prices up, not down.
Here is how that works, in plain terms.
Where rates are today
For the week of October 22, 2026, the average 30-year fixed rate was 7.32%, according to Freddie Mac. A year earlier it was 6.19%. So a 5% rate would be a big drop from where we are now.
I don't predict rates. This post is a "what if." If rates did fall to 5%, here is what the economics say would happen, step by step.
Step one: buyers get more buying power
Most buyers shop by monthly payment, not by price. Lower rates make the same payment go further.
Here is a simple example. These are round numbers to show the idea, not a loan quote. Take the September 2026 Madison area median single-family price of $508,950 and a 20% down payment. That leaves a loan of about $407,000. The monthly principal and interest on a 30-year loan would be about:
At 7.32%: $2,797
At 6%: $2,441
At 5%: $2,186
That is about $600 a month less at 5%. Flip it around: a buyer who can pay $2,797 a month could borrow about $521,000 at 5%, instead of about $407,000 today.
That extra buying power brings more people into the market. The National Association of REALTORS estimated that a 6% rate alone would make the median-priced home affordable for about 5.5 million more U.S. households, including 1.6 million renters. The National Association of Home Builders found that even a small cut, from 6.25% to 6%, would bring about 1.42 million more households into the market. A drop all the way to 5% would be much bigger than either of those.
Step two: some sellers come back, but not most
Lower rates also help sellers. Many owners stay put because selling means trading a low rate for a high one. This is the "lock-in effect."
But look at what rates owners already have. In the second quarter of 2026, according to a Realtor.com analysis of federal mortgage data:
19.2% of mortgages had a rate below 3%.
29.9% were between 3% and 4%.
16.5% were between 4% and 5%.
12.0% were between 5% and 6%.
22.5% were at 6% or higher.
Add up the first three, and 65.6% of owners have a rate below 5%. For those owners, a 5% rate still means a higher rate if they move. So a 5% rate would ease the lock-in, but it would not end it.
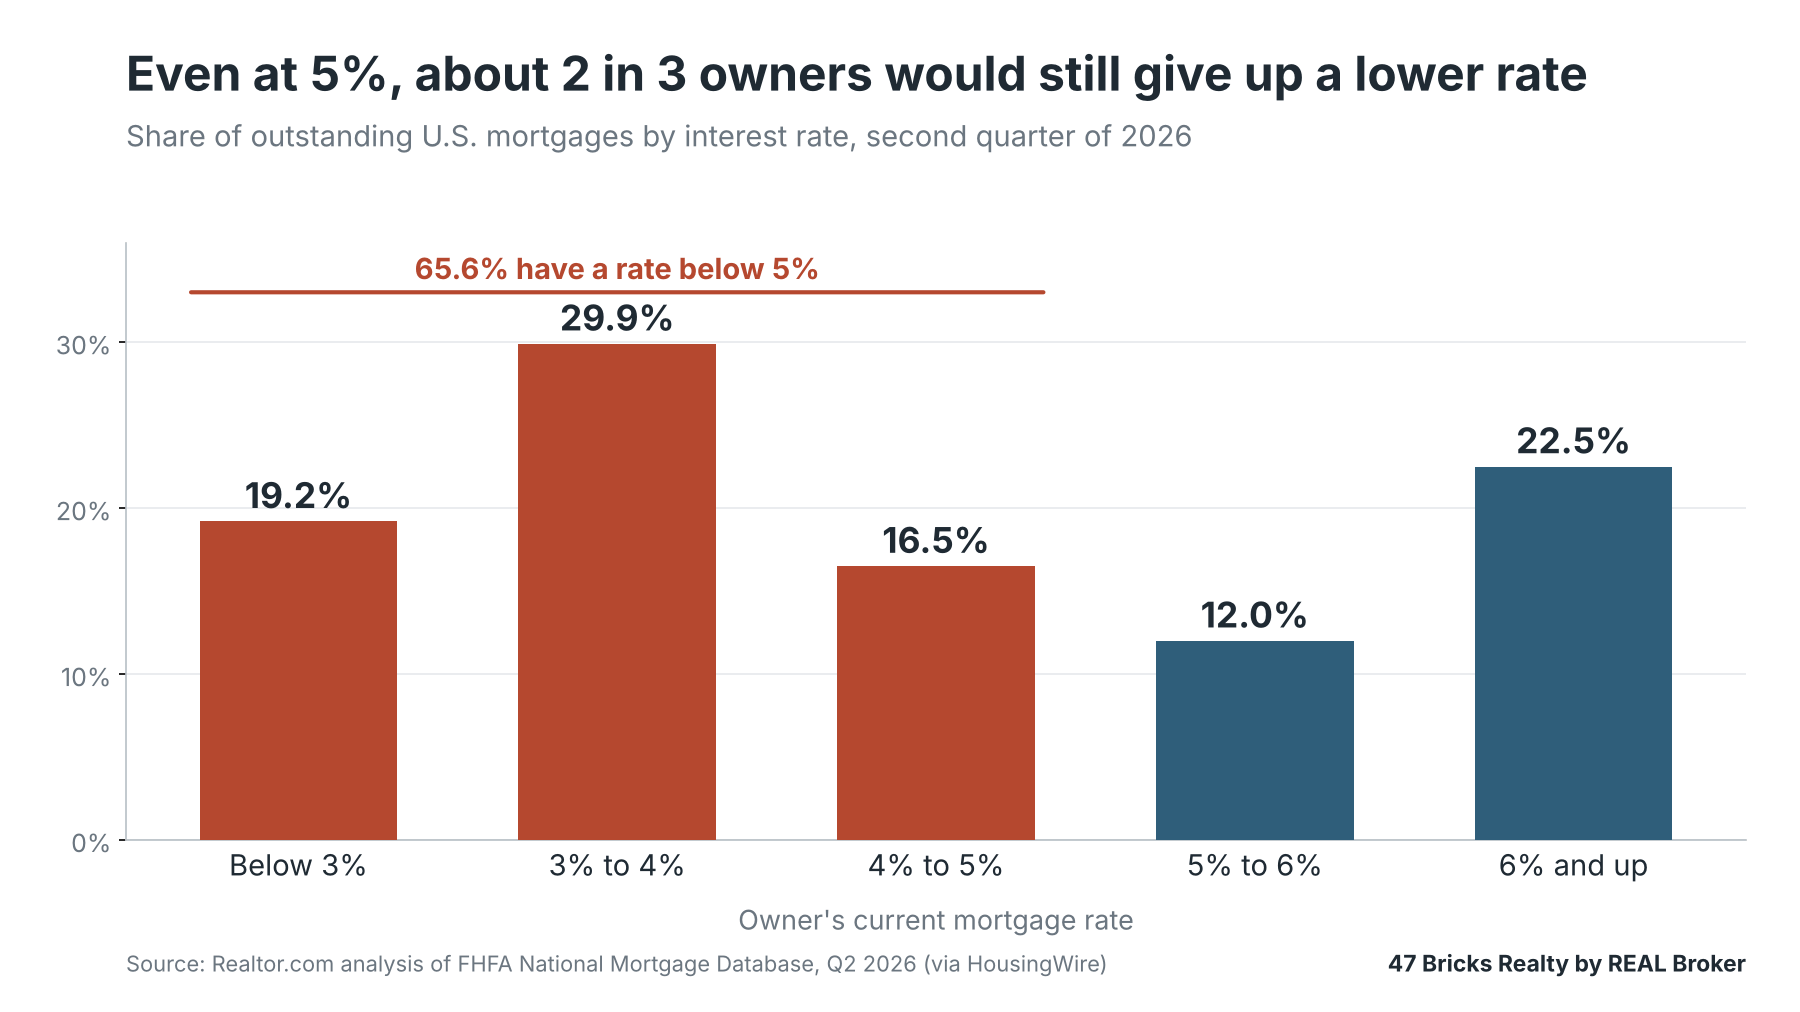
Step three: more buyers than new sellers
This is where supply and demand come in. Prices depend on how many buyers there are compared to how many homes are for sale.
Here is where the Madison area single-family market stood heading into fall, based on South Central Wisconsin MLS data:
937 homes were for sale in early October, up 8% from a year earlier.
That is about 2.1 months of supply. A balanced market is usually about 4 to 6 months.
The September median price was $508,950, up 6% from $480,000.
Accepted offers in September fell 15%, from 431 to 367.
So even with rates above 7%, homes are still scarce here. Now picture a 5% rate. The pool of buyers grows a lot. The pool of sellers grows some, but most owners still have a lower rate. More buyers competing for a small number of homes is the classic setup for rising prices.
We have seen a version of this before. In August 2021, when rates were very low, 38% of Madison area contracts involved multiple offers. In August 2026, it was 24%. Lower rates tend to bring bidding wars back.
What would keep prices from jumping?
A 5% rate does not have to mean a price spike. Here is what would have to happen for prices to stay steady even with lower rates:
A big wave of listings. If the 34.5% of owners with rates of 5% or higher, plus owners who simply need to move, listed at the same time, supply could catch up with demand.
Weaker local jobs. Rates often fall when the economy slows. If a slowdown cost a lot of local jobs, fewer people would be ready to buy, even at 5%.
More homes being built. Lower rates help builders too. Years of building more homes than new households would ease the pressure.
Without one of those, the more likely result of cheaper money is more competition for the homes that are for sale.
A note on "waiting for 5%"
Many buyers have 5% in mind as a target. Mad City Dream Homes cited national data from Keeping Current Matters showing that 63% of buyers consider a "good" rate to be less than 5%.
The catch is that if rates do get there, you won't be the only one who noticed. You may get a lower payment but face more competition and a higher price. Some buyers use a temporary rate buydown instead. With a 2-1 buydown, the rate is 2 points lower in year one and 1 point lower in year two, then goes back to the full rate in year three. It helps early on, but it is not a long-term fix.
What this means for you
If you're buying: A lower rate cuts your payment, but it can raise the price you pay. Run the numbers both ways, and remember you may be able to refinance later if rates fall.
If you're selling: Lower rates would likely bring more buyers to your door. But you don't need to wait for them; homes priced right still sell today.
If you're a homeowner with a rate above 5%: A drop to 5% could open the door to a refinance or a move. Know your numbers so you can act if it happens.
Have a question about your own situation? Call or text me at 608.213.3654.
Sources
Freddie Mac, Primary Mortgage Market Survey: Mortgage Rates Decrease to 7.32% (October 22, 2026)
HousingWire, Mortgage rate lock-in effect has yet to release its grip, Realtor.com analysis finds (October 23, 2026, FHFA National Mortgage Database data)
Mad City Dream Homes, Madison Area Single Family Home Trends for September, 2026 (South Central Wisconsin MLS data)
National Association of REALTORS, What Mortgage Rate Will Get More Buyers Moving? (July 17, 2025)
National Association of Home Builders, Pricing in 1.42 million Households: Effects of a 25-Basis-Point Mortgage Rate Cut (February 2026)
Mad City Dream Homes, What is a good interest rate? (August 21, 2026, citing Keeping Current Matters)
Mad City Dream Homes, 5.25% Interest Rates for a Limited Time (October 26, 2026)